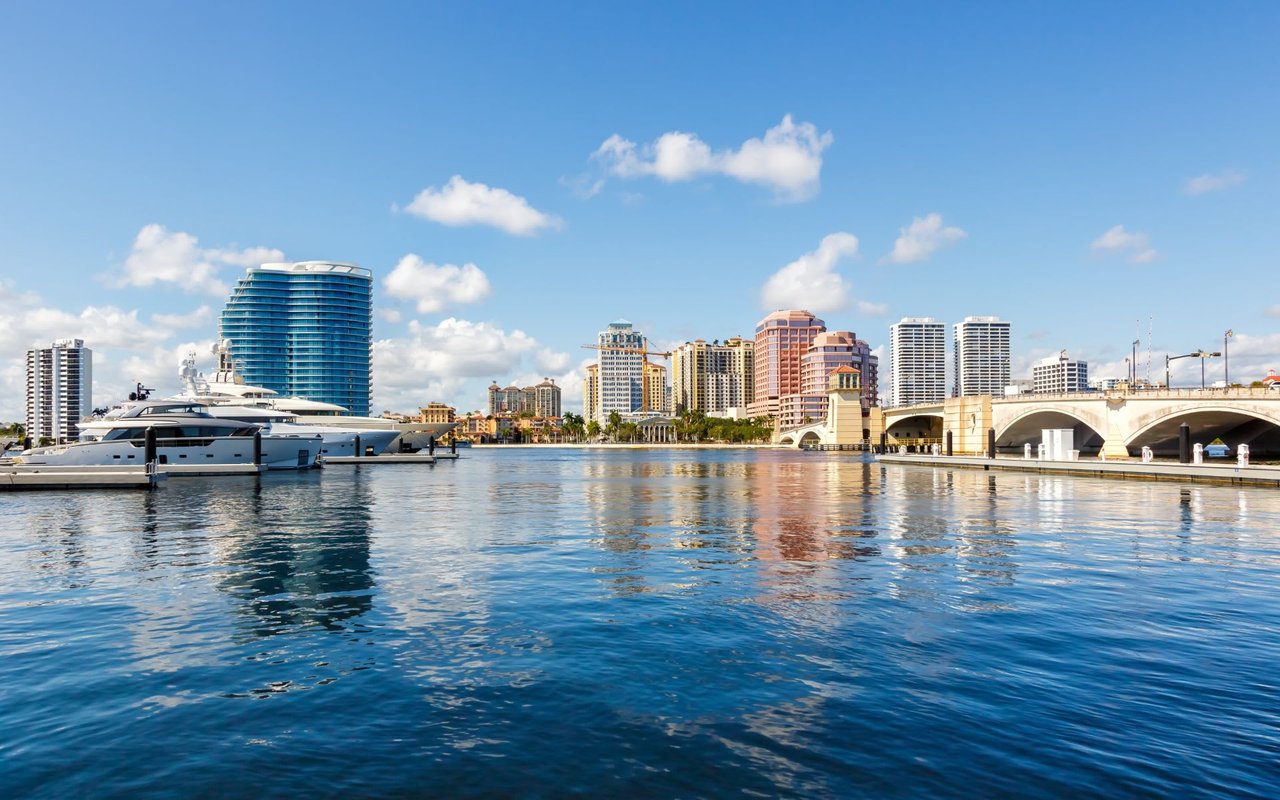
The Palm Beach County Property Appraiser valued most of the 27 Southbridge condominiums at less than $250,000 each. Late last year and into January, an affiliate of Related Ross bought those same 27 units for $25.4 million, or nearly $941,000 per unit, The Real Deal reported. Southbridge is a three-story complex at 3915 South Flagler Drive. It was built in 1981 and sits on 1.3 acres along the Intracoastal Waterway.
That gap is the market on this stretch of shoreline. An older waterfront unit can carry two values. One is what a resale buyer would pay for the apartment. The other is what a developer would pay for the unit's share of a site that can't be replaced. Which value an owner ends up receiving depends on a Florida statute that gives a small group of neighbors the deciding vote.
Two prices for the same unit
Related Ross had already bought 18 Southbridge units in 2024 and 2025 before the January purchase. That brings it to 45 of the building's 63 condos, at a total cost of $37.3 million, or roughly $829,000 per unit. The Real Deal described the position as a likely redevelopment play.
A buyer pricing a Southbridge-style unit on condition, finishes, and recent resales would land near the appraiser's figure. A developer assembling the site priced each unit as a piece of shoreline. The 18 units Related Ross doesn't own now sit between those two numbers, and the building's vote will decide which number applies.
What 2026 has looked like on Flagler Drive
These are the year's bulk deals and attempts, with the terms reported by the Palm Beach Post and The Real Deal, including the Real Deal's coverage of the Green Terrace auction.
| Building | Address | Built | Units | Reported price | Status |
|---|---|---|---|---|---|
| Southbridge | 3915 S. Flagler Dr. | 1981 | 63 | $25.4M for 27 units, about $941K each | Related Ross holds 45 of 63 |
| Harbor Towers | 3901 S. Flagler Dr. | n/a | 61 | About $100M | Buyout closed by Fort Partners |
| Portofino South | 3800 Washington Rd. | 1971 | 140 | $295M, about $2.1M per unit | Nov. 3 offer deadline; more than 20 holdouts reported in September |
| Flagler Yacht Club | 3701 S. Flagler Dr. | n/a | 39 | $150M to $180M, terms as of February | Targeted by BEKO Equities |
| La Fontana | 2800 N. Flagler Dr. | 1961 | 140 to 144 | Roughly $190M to $200M | Contract ended in October |
| Green Terrace | 2800 Georgia Ave. | n/a | 84 | $13.5M, about $161K per unit | Sold through bankruptcy auction |
Harbor Towers shows how hard these sites are fought over. It is a two-acre, two-building complex across the water from Mar-a-Lago. Nadim Ashi's Fort Partners and Steve Ross's Related went to court over control of it in 2025. After a settlement that October, Fort Partners went ahead with the condo termination, and The Real Deal reported in February that the buyout would total about $100 million. Southbridge, owned largely by Related Ross, is next door at 3915.
The arithmetic of a veto
A termination doesn't need every owner to agree, and it can't pass with a simple majority either. Under Section 718.117 of the Florida Statutes, a residential association's optional termination plan must be approved by at least 80 percent of the total voting interests. If 5 percent or more reject it, by negative vote or written objection, the plan cannot proceed. Every voting interest counts, and none can be suspended for the vote.
In a 140-unit building, 5 percent is seven owners. Portofino South shows what that means for a deal this size. The 12-story building at 3800 Washington Road was finished in 1971 and overlooks the Intracoastal. BEKO Equities is a joint venture of Gilbert Benhamou's Miami-based Immocorp and Hong Kong-based O.D. Kobo. It offered $202 million in January, then raised the offer to $295 million, which it called its "best and final," according to the Palm Beach Post. That works out to about $2.1 million per unit. In September, BEKO said it had agreements with more than 60 percent of owners, and the offer deadline had been extended to Nov. 3.
The holdouts told the Post in mid-September that there were more than 20 of them, roughly three times the seven needed to block. Meanwhile, every owner was paying for an aging building. Assessments came to roughly $10 million, including $3.5 million for elevator repairs, according to The Real Deal. That outlet tied the high assessments at older condos to the tighter rules passed after the 2021 Surfside collapse.
The statute also sets a time cost on a no vote. When 5 percent or more reject a plan, a new plan under that subsection can't be considered for 24 months after the rejection. A blocked plan closes the statutory route to termination for two years, and assessments keep coming due in the meantime.
What the statute guarantees once a bulk owner reaches 80 percent
The rules change when a single owner, or related entities, holds at least 80 percent of the voting interests at the time the plan is recorded. In that case, Section 718.117 sets out protections for everyone else:
- Fair market value as a floor. Every owner other than the bulk owner must receive at least 100 percent of the unit's fair market value. An independent appraiser chosen by the termination trustee sets it, as of a date no earlier than 90 days before the plan is recorded.
- Original purchase price for homestead owners. If an owner has a homestead exemption and is current on assessments and other association obligations, fair market value must be at least what that owner paid for the unit.
- A relocation payment. Former owners with homestead status receive an extra 1 percent of the termination proceeds allocated to their unit, paid by the bulk owner.
- A year to stay. If the former units are offered for lease to the public, owners living there may lease their own unit for 12 months on the same terms. They must request it in writing within 90 days of the plan being recorded.
- Mortgage payoff. The plan must pay the first mortgage up to the unit's share of the proceeds. For an owner who is current on assessments, other association obligations, and the mortgage itself, the lender's receipt of the unit's share or the outstanding balance, whichever is less, satisfies the first mortgage in full.
The statute's definition of fair market value explains why the Southbridge number matters beyond Southbridge. It counts "similar units sold in other condominiums, including units sold in bulk purchases." It also excludes units "acquired in bulk following a bankruptcy or foreclosure." Negotiated bulk prices can therefore become comparables for the next appraisal, and distressed bulk prices cannot.
This is general information. It isn't legal, tax, or financial advice, and owners or buyers in a building facing a termination plan should review their own situation with a Florida real estate attorney and their tax advisor.
The forced sale that sets the low end
Green Terrace shows the price when a building reaches the end without a negotiation. Its association filed for bankruptcy in April 2025, after the city claimed $1.4 million in unpaid water bills and $1.5 million in code enforcement violations. All 84 units at 2800 Georgia Avenue then sold at a bankruptcy auction for $13.5 million, about $161,000 per unit. The buyer was Green Terrace Owner LLC, an entity linked to Woodfield Development partner Ross Abramson.
So in one year, West Palm Beach bulk sales ranged from about $161,000 per unit at a bankruptcy auction to an offer of about $2.1 million per unit for an Intracoastal building in the middle of a negotiation. The difference came from the waterfront and from whether owners kept the right to vote on the sale.
Why the land is worth more than the buildings on it
The Real Deal links the wave of buyouts to two things. There is little undeveloped waterfront land left in South Florida, and more owners are willing to sell as the post-Surfside repair and reserve requirements raise costs. The same October report counted more than a dozen luxury condo projects in the West Palm Beach pipeline, totaling over 2,000 units. Many come from Miami-based developers, including Related Group, Terra, and BH Group.
Most of that new product is still to come. Alba is the exception: its developer marked a grand opening on Aug. 17, 2026. An October tracker of downtown projects listed Mr. C Residences and South Flagler House estimated for 2027 and Olara and the Ritz-Carlton Residences for 2028. Each of those towers needed a site, and the sites still available on Flagler Drive mostly have 1960s and 1970s buildings on them.
La Fontana shows that a signed deal doesn't guarantee a closing. The 1961 co-op at 2800 North Flagler Drive had a contract with Chuck Whittall's Unicorp National Developments. The Palm Beach Post reported that the sale ended on Oct. 19, after owners declined to extend the buyer's deadline. The building's broker told The Real Deal that several other developers were interested in the site and ready to make offers.
Questions buyers ask about these buildings
Does a developer's offer mean a unit will sell for that price? No. An offer becomes a payout only when 80 percent of the voting interests approve a plan and fewer than 5 percent reject it. La Fontana's contract ended in October, and Portofino South's holdouts reported more than enough votes to block in September.
Can bulk sales in other buildings affect a unit's appraised value in a termination? The statute's definition of fair market value includes units sold in bulk purchases in other condominiums. It excludes bulk acquisitions that follow a bankruptcy or foreclosure.
What happens to assessments while a vote is pending? They keep coming due. Portofino South owners carried roughly $10 million in assessments while the buyout was negotiated, including $3.5 million for elevator repairs.
If you are weighing an older unit on Flagler Drive or Washington Road, or you own one and a developer's letter has arrived, the useful questions concern the building's vote count, its assessment schedule, and its bulk-sale history as much as the floor plan. I'm glad to go through those details with you at Breakers West Properties, so your decision rests on how the building's ownership is actually set up.